AI Engineering · Quant Finance
Investment Copilot
Investment research is scattered across data sources, scoring models, and execution platforms — slow to go from idea to a tested position.
- My role
- Solo project — architecture, agent, scoring model, and execution loop.
- When
- 2025
+11.4%
paper return, 6 months (bench. +7.2%)
1.3
Sharpe ratio
−6.8%
max drawdown
45 s
to draft a research memo per ticker
Approach
Bloomberg/FactSet ingestion, a LangChain agent on local LLMs that drafts research memos, multi-factor scoring over a 500-stock universe, and IBKR paper trading — all behind one Streamlit UI.
Results
Over six months of paper trading, the factor-scored portfolio returned +11.4% against +7.2% for its benchmark, with a Sharpe of 1.3 and a maximum drawdown of −6.8%. The agent drafts a structured research memo per ticker in about 45 seconds, entirely on local models.
Architecture
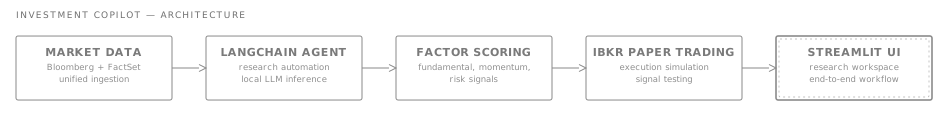
Technical highlights
- 01LangChain agent with tool use over market data
- 02Multi-factor scoring with configurable weights and ranking
- 03IBKR paper-trading integration for execution simulation
- 04Local LLM inference — no external API dependency
Stack
Related case studies
AI Engineering · Agents
AI Agents Toolkit for Index Operations
46
reusable skills across 5 agents, in daily use
AI Engineering · Agents
Aloi, a Market Research Agent that Checks its Figures
27/28
eval questions passed with no figure missing from the fetched data (one run)
AI Engineering · Developer Tools
AgentDeck, One Place to Answer Your Coding Agents
1 place
to answer Claude Code and Codex, on the PC or from a phone