Quant Risk · MLOps
EVT Pre-Trade Limits Recalibration
Static pre-trade limits fired on perfectly normal trades — hundreds of false alerts a day — while still missing genuinely extreme orders.
- My role
- Designed the model and the backtesting framework; built the pipeline and dashboards; handed over to the Market Access team.
- When
- Feb – Aug 2025
94%
precision @ 1.3% FPR
−87%
false alerts vs static limits
€1.8M
risk-weighted assets released
80%
faster processing
Approach
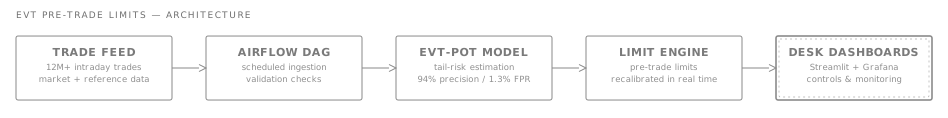
Peaks-over-Threshold model (Generalized Pareto on the tail) fitted on 12M+ trades to set dynamic size/price limits per instrument, backtested against the static rules and shipped with tests, monitoring, and CI/CD.
Results
94% precision at a 1.3% false-positive rate on extreme-event detection across the pre-trade limit perimeter. False alerts fell by 87% versus the static limits, better-calibrated thresholds enabled a EUR 1.8M RWA release, and processing time dropped 80%. Deployed to production with a full MLOps stack.
Architecture
Technical highlights
- 01Peaks-over-Threshold (POT/GPD) modeling of tail behaviour per instrument
- 02Backtesting against the static rules, with Kupiec-style exception tests
- 03MLOps packaging: unit tests, Docker, GitHub Actions, monitoring hooks
- 04Validation framed around what the desk cares about: false positives, risk sensitivity, usability
Stack
Related case studies
AI Engineering · Quant Finance
Investment Copilot
+11.4%
6-month paper return vs +7.2% benchmark
AI Engineering · Deep Learning
GPT from Scratch
10.8M
parameter decoder-only transformer, built from zero
Data Platforms · Operations
Index Rebalancing Monitoring Platform
7
Streamlit views replacing Excel tracking